Digital Euro: The hidden risks to your money and your privacy
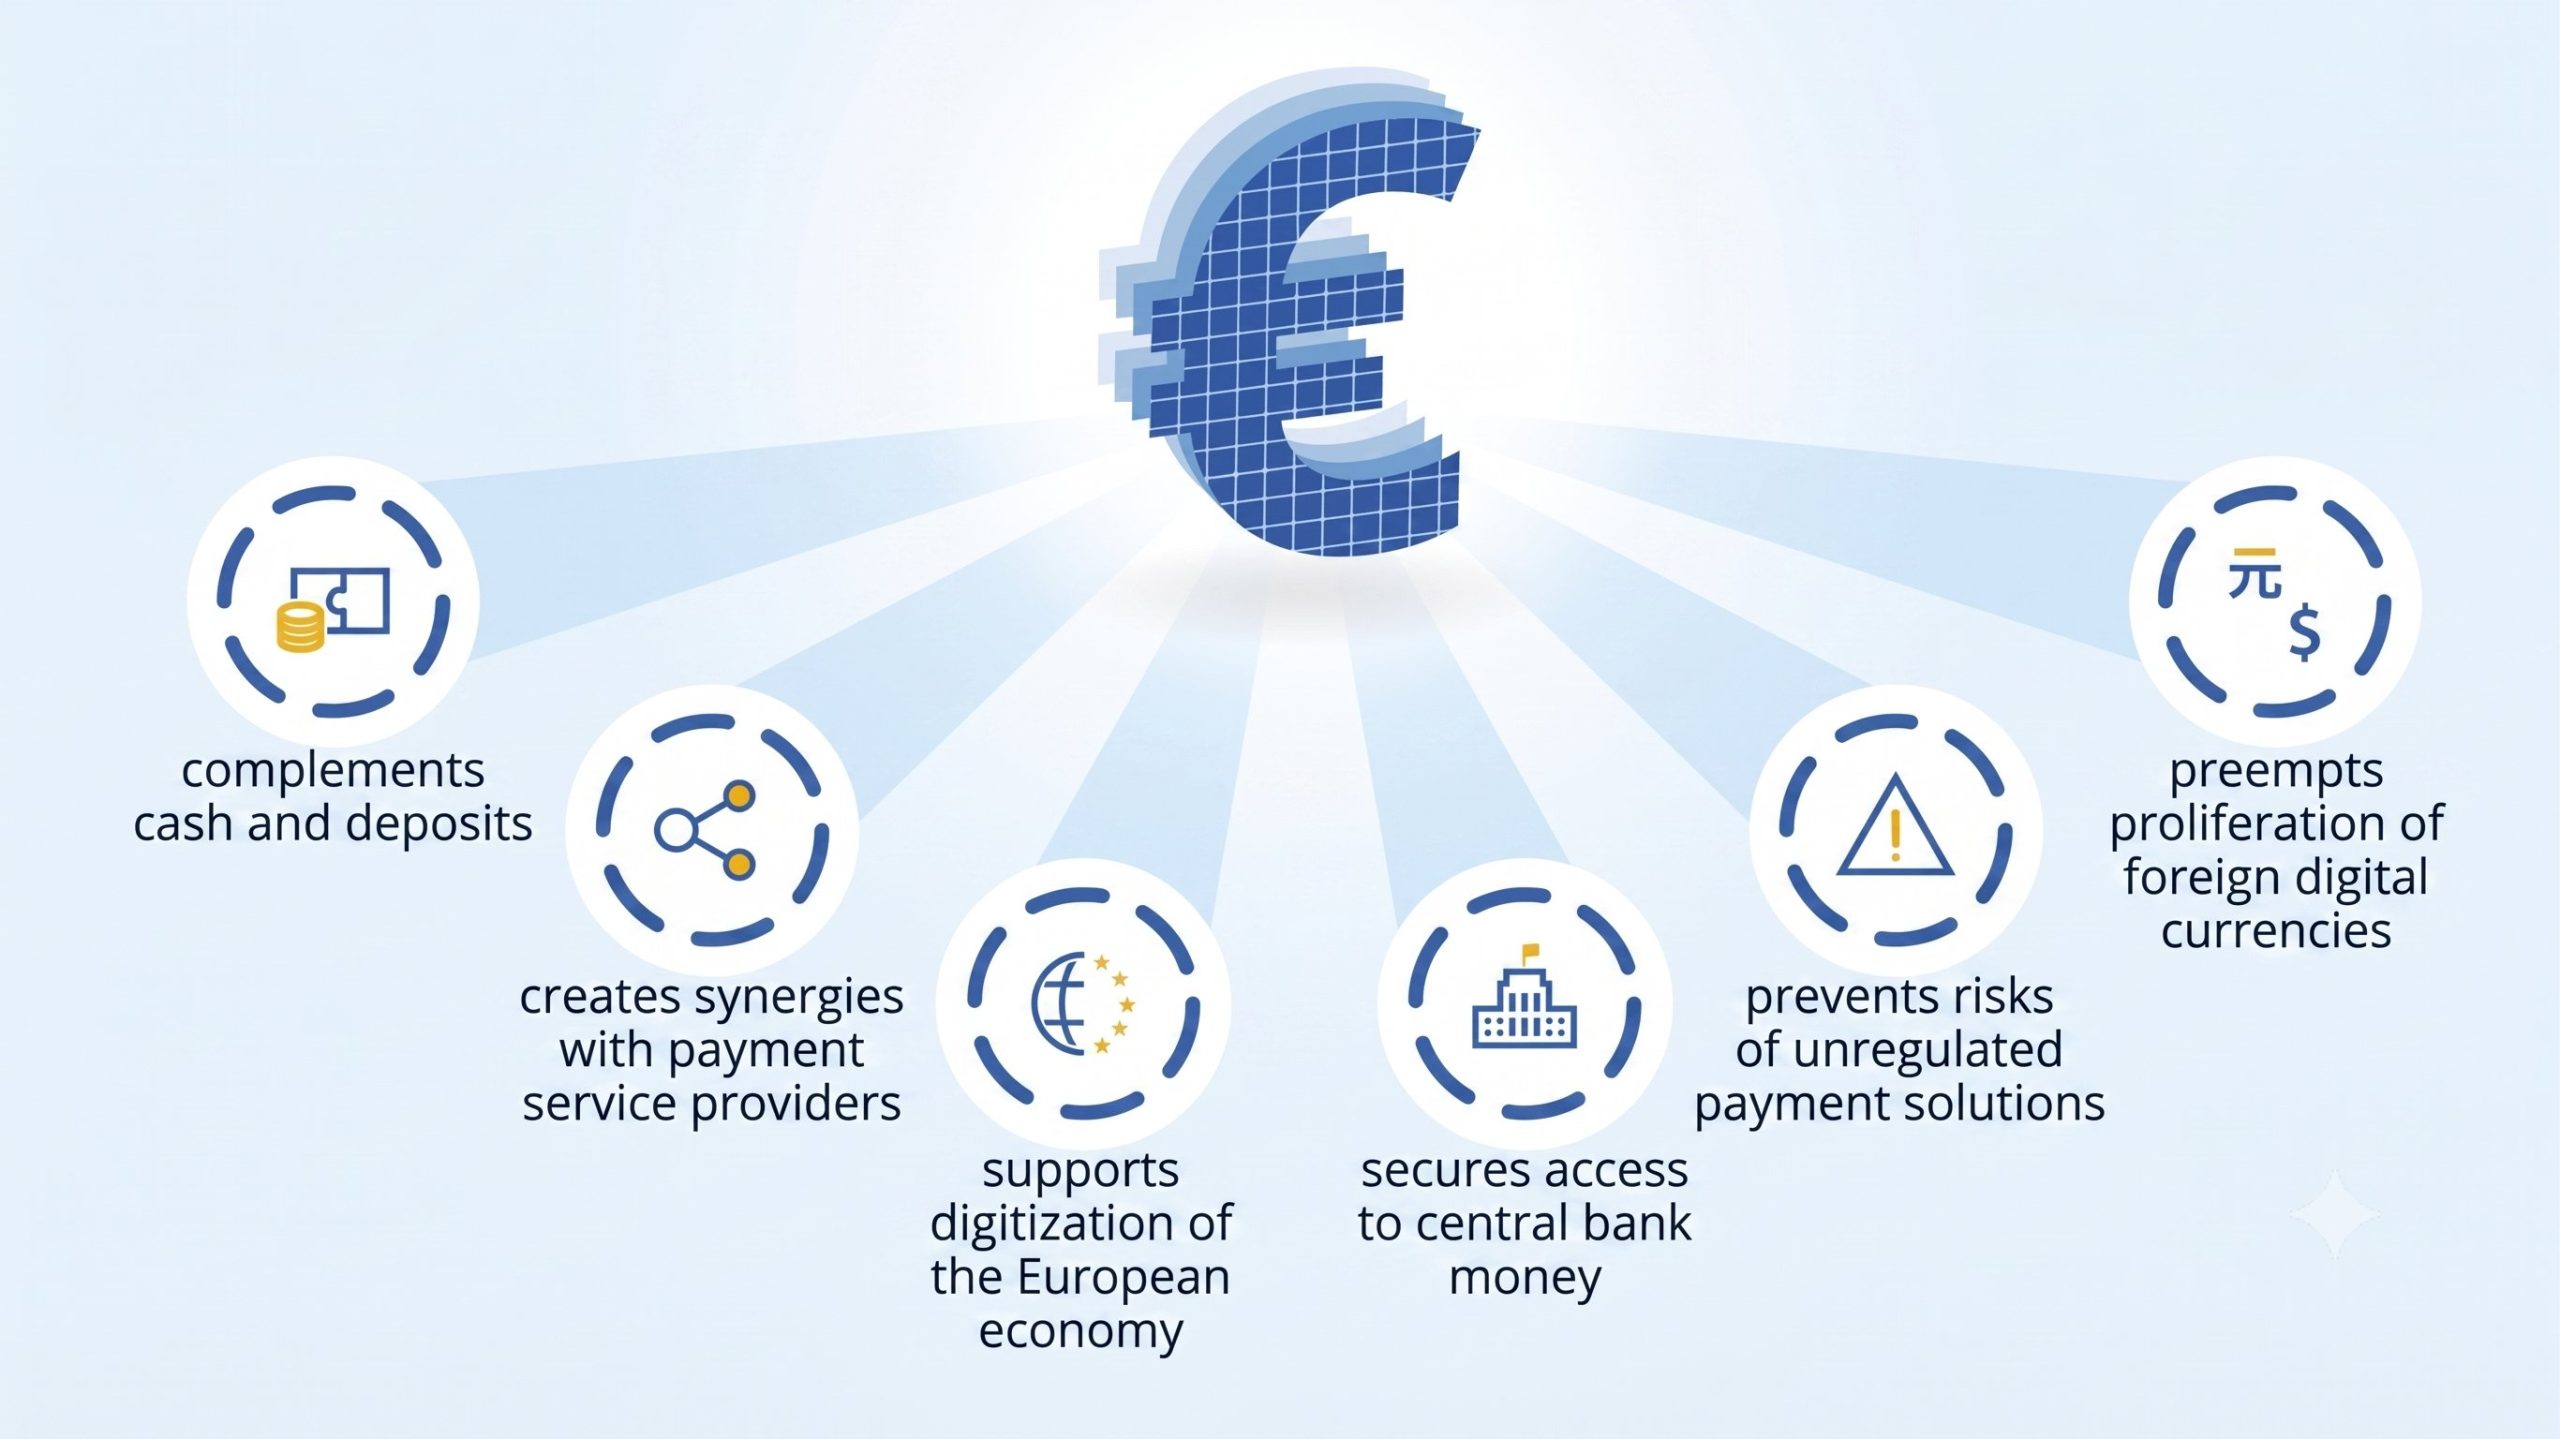
Modern, convenient, secure – that’s how the digital euro is often presented. But behind this facade lie questions that hardly anyone talks about openly. Who will be able to track your every payment in the future? Will the authorities be able to dictate how much digital money you’re even allowed to own? The digital euro could change our relationship with money in ways we can hardly imagine today.
This article explains what the digital euro really is, when it will arrive – and, above all, what specific dangers it poses to your privacy and your assets. From surveillance and holding limits to the potential abolition of cash: the risks are real, and they affect everyone.
What is the digital euro and when will it be released?
Digital Euro: Definition and basics
The digital euro is not cryptocurrency, not a PayPal clone, or a new app from your bank. The European Central Bank (ECB) envisions it as a digital form of cash – central bank money issued and guaranteed by the ECB, just like the banknotes in your wallet today. As legal tender, it must (or should) be accepted everywhere in the Eurozone.
It will be used via an electronic wallet, which you set up with your bank or a payment service provider. Your digital money will be stored there. Basic services—especially making payments – will be free of charge.
It will work both online and offline. Even during a network outage, you could continue making payments as long as your smartphone has power. However, there is already a catch: a limit of €3,000 is being considered. You would not be allowed to keep more than this amount in your digital wallet – more on that later.
Current rollout schedule
The project has been underway since October 2021. Following an investigation phase that lasted until October 2023, the preparatory phase ran from November 2023 to October 2025. The technical foundations are to be established starting in November 2025.
In parallel, the EU Council and the European Parliament are working on the legal framework. The Economic and Monetary Affairs Committee and the plenary have already given their approval. The legal framework is expected to be adopted by the end of 2026 (framework adoption is not yet final).
A pilot project with banks and retailers could begin in mid 2027. Public implementation is realistically not expected before 2029 – and only if the legislative process is completed.
Difference to cash and cryptocurrencies
Three comparisons help to put the digital euro into perspective.
Compared to cash: The digital euro exists only electronically. However, like cash, it is guaranteed by the central bank and accessible to everyone – without any account requirements.
Compared to Bitcoin and other cryptocurrencies: The difference is fundamental. Cryptocurrencies are decentralized, subject to strong price fluctuations, and are not backed by any single entity. The digital euro is issued and controlled centrally by the ECB; its value remains stable and is pegged one-to-one to the physical euro.
Compared to current card payments: This is where it gets interesting. When paying by card or bank transfer, you have a claim against your bank. With the digital euro, this claim would be directly against the ECB. This would make it more secure than regular bank deposits in a crisis – neither a bank failure nor the collapse of a payment service provider could jeopardize it.
So far, so good. But this is precisely where the questions begin that the ECB prefers not to ask aloud.
Hidden risks to your privacy
Monitoring through central payment data
Digital payments leave a trace. Every transaction with the digital euro is recorded – at least for online payments. Payment service providers and banks must be able to track transactions, as required by anti-money laundering regulations.
With cash, no one knows what you do with it. With digital payments, there’s always someone who knows. And that’s precisely the problem: Who exactly has access to this data? Data protection advocates are already warning that digital central bank money could lead to increased profiling and surveillance.
Loss of anonymity when paying
Cash is discreet. No one knows where you spent your money. PayPal, Visa, Mastercard – they all collect and analyze your payment data. The digital euro doesn’t improve matters.
Complete anonymity is impossible. While the Eurosystem can’t directly identify you with online payments, your bank sees exactly where you spend your money. That’s not a small difference – it’s the crux of the problem.
Government access to transaction history
The Berlin Group, an international data protection working group, is sounding the alarm. It warns of unprecedented government access to citizens’ financial data. Governments, central banks, financial institutions – they could all theoretically view your transaction history.
The German Federal Ministry of Finance disagrees: The ECB and other central banks will not be granted access to personal data. A risk-based approach is planned for everyday payments, designed to protect privacy as much as possible. Whether this will hold up in practice remains to be seen.
Data protection: What the ECB promises
The ECB makes clear promises: The highest data protection standards, no linking of online payments to individuals, and only pseudonymized data for the Eurosystem. Your bank will receive only the minimum information required by EU law.
That sounds solid. But promises and reality are very often two different things – especially when it comes to data.
Offline payments as a solution?
Offline payments would be the exception that truly offers protection. Only you and the recipient would know about the transaction – similar to cash. The catch: Both the number and the amount of such payments will be limited. This is not a true replacement for the anonymity of cash.
Danger to your money and the banks
Holding limits restrict your assets
How much digital euro are you allowed to hold? The Bundesbank is currently discussing limits between 500 and 3,000 euros. That sounds like a small amount – and it is. Many Germans have significantly more than 3,000 euros in their checking accounts.
This limit applies exclusively to the balance in your digital wallet, not to individual payments. Want to transfer larger amounts? It’s possible – the system automatically tops up your balance from your bank account. But how much you’re allowed to have readily available will be determined by someone else in the future.
Risk of a digital bank run
A digital bank run unfolds faster than anything we’ve ever seen before. No queuing at the bank counter, no waiting. Anyone wanting to secure their money during stressful times can do so with just a few clicks – en masse, simultaneously. Households surveyed openly admit to planning exactly that: In a crisis, they would withdraw more cash as soon as the digital euro is available.
The collapse of Silicon Valley Bank demonstrated how quickly such dynamics can develop. Cash, at least, still has physical boundaries. The digital euro does not.
Banks lose deposits and business model
Banks operate on a simple principle: customer deposits in, loans out. If these deposits flow to the ECB instead, the capital for lending is lacking. Studies show that the return on equity drops noticeably – especially for smaller banks.
To put it in figures: If every household held € 3000,- in digital euros, banks would lose between 1.35% and 1.62% of their capital per year. The result would be higher borrowing costs – for individuals as well as businesses (Source: Universität Würzburg: Der Digitale Euro Nutzen, Kosten und Risiken).
Potential negative interest rates on digital money
Economists face a dilemma: The digital euro must be attractive enough for people to use it – but not so attractive that bank deposits leave en masse. Achieving this balance is considered virtually impossible.
Negative interest rates could be used as a steering mechanism. This sounds technical, but in concrete terms, it means your digital assets will lose value over time. Quietly, systematically – and completely legally.
Further hidden risks of the digital euro
Technical dependency and cyber risks
No electricity, no internet – no digital euro. The offline function exists, but it’s limited. Anyone who wants to access their money during a prolonged power outage is simply out of luck.
There’s another risk, too: Attacks on digital payment systems could increase. The ECB promises state-of-the-art technologies to protect against cyberattacks. But no digital system is invulnerable – that has never been the case, and it never will be.
Programmable money: Myth or danger?
Imagine your money works like a voucher. You can only spend it on specific purposes, nothing else. The ECB is clear: That’s not how the digital euro will work. What banks could offer, however, are so-called conditional payments. Whether that will ultimately make a difference remains to be seen.
Harmonisation of European payment systems
Visa, Mastercard, PayPal – American corporations currently dominate the European payments market. The digital euro is intended to change that and reduce dependence on these companies. It would contribute to European sovereignty. That sounds reasonable – as long as the alternative doesn’t mean even more centralized control.
Abolishing cash through the back door
The ECB assures that cash will not be replaced. Critics don’t believe it. Slovakia enshrined the right to cash payments in its constitution in 2023 – simply because its members of parliament distrusted the assurances from Frankfurt. It is remarkable when an EU member state deems this step necessary.
Conclusion
The digital euro is coming – whether we’re ready or not. Data protection gaps, holding limits, cyber risks, potential negative interest rates, and a gradual phasing out of cash: These aren’t speculations, but concrete scenarios that economists, data protection advocates, and even some governments are already taking seriously.
There’s still time until 2029. Use it wisely. Follow the decisions made in the EU legislative process – because that’s where the course will be set. Those who stay alert now will be better able to assess later what the digital euro actually means for their money and their privacy.
FAQs
Q1. What will happen to my savings when the digital euro is introduced?
Your existing savings in bank accounts remain unchanged. The digital euro is an additional payment option, not a replacement for your bank balance. However, there will likely be a holding limit of € 500,- to € 3000,- for digital euro balances. You can still only keep higher amounts in your regular bank account.
Q2. Is the digital euro dangerous for the financial system?
There are risks to financial stability. In times of crisis, citizens could quickly transfer large amounts of money from bank accounts into digital euros, which could lead to a digital bank run. Furthermore, banks lose deposits that they need for lending, which can result in higher borrowing costs.
Q3. Will my payments with the digital euro be anonymous?
Complete anonymity like with cash is impossible. While the ECB cannot directly identify you with online payments, your bank will always know what you are spending your money on. Only offline payments would offer cash-like privacy, but with limitations on the number and amount of transactions.
Q4. Could the digital euro lead to the monitoring of my spending?
Yes, the risk exists. Every digital transaction leaves traces that payment service providers must track. Data protection advocates warn of increased profiling and surveillance. Governments and financial institutions could theoretically gain access to transaction histories, even though the ECB promises the highest data protection standards.
Q5. Will the digital euro lead to the abolition of cash?
The ECB assures that cash will not be replaced. Critics, however, fear a gradual phasing out of cash. Some countries, such as Slovakia, have already enshrined the right to cash payments in their constitutions because they distrust the ECB’s announcements.
Sources & links
Digitaler Euro – was ist das und wozu dient er?
Einführung Digitaler Euro: Was er bedeutet – und was er Ihnen bringt
Auf einen Blick: Digitaler Euro